Uncategorized • October 31, 2025

American Mobility is Becoming Prohibitive

The Wall Street Journal recently had a spectacular instagram post that really succinctly captures the difficulties that we have faced within the real estate market: lack of mobility. Mortgage rates are nearly twice as high as they were during COVID. Employers are not fighting for new employees anymore. Quiet quitting is no longer a common phrase. If anything, many employees are happy to not be losing their jobs.

So what does this look like within our market? It looks like low inventory coupled with lower demand. The consequence of this is low price growth and not too many transactions. Good news: many homeowners have low rates and a lot of equity. The pressure to sell, negotiate, and mobilize our market doesn’t necessarily exist.

For insight into the predictive changes surrounding the Fed’s path for interest rates, come back next week!!

Uncategorized • October 8, 2025

Not Increasing Rent. How Much Are You Losing?

If you aren’t incrementally increasing rents, you could be losing more money every year that goes by. Your property taxes increase and wear and tear is a regular expense.

Between property taxes and ongoing maintenance costs like water heaters, appliance repair and replacement, leak repair, etc, expenses with property ownership can grow. This doesn’t even include the amount of repair after a tenant leaves. Those can be major deterrents to life as a landlord. 

However, if you do small, incremental rent increases, you can mitigate some of those unforeseen expenses. Also, if you do this every year, you can teach your tenant to expect increases to their rent every year and never have the difficult, “why is my rent going up” conversation again all while collecting more rent!!

The big question now, how far off market rent are you? Is it best to work with your tenant? Maybe it’s not worth it and it’s time to replace your property for one that is currently generating market rent. Contact me today to help you walk through this decision making process. 

Uncategorized • July 11, 2025

Mid Year Market Update

Can you believe it!! We’re already half way through 2025. Time to look at how our market has changed. As a point of reference, I’m going to include and highlight my notes regarding the subjects from the beginning of the year.


Rates

Yes the fed has dropped the federal funds rate. However, according to Mortgage News Daily , mortgage rates haven’t progressively decreased. As of right now, the expectation is for two more fed rate cuts. This doesn’t directly correlate to lower mortgage rates. At a minimum, the hope is for mortgage rates to not increase.

We’re halfway through the year and we have not yet received any rate changes. There appears to be some amount of conflict between the Fed Chair Jerome Powell and President Donald Trump. Trump vehemently wants lower rates. Powell expresses concerns regarding tariffs and how those changes will affect our economy. There is still some level of hope for two rate cuts. That being said, according to Mortgage News Dail, rates are roughly down by about half a point.


Rent growth opportunity for first half of 2025

Because inflation has still been relatively high, most landlords will be able to increase rents by 8.9% until July 31, 2025. The general rule of thumb is 5% plus CPI with a cap of 10%. This doesn’t mean that all rents are up by 8.9%. Given that CPI is likely to come down with the Fed’s effort to combat inflation, there might not be opportunity to charge rent at an increase of 8.9%. It is probably most applicable for long term tenants who are currently under market.

For the upcoming year and in Orange County, the allowable rent increase is 8%. This indicates that CPI is at 3% and that inflation is slowly coming down. This ought to provide a little relief to tenants as well as continued growth for landlords.


Year over Year changes in Sales Price

Over the course of the past year, our average sale price slumped by nearly 20%. This is a good reflection of lower rates having a strong impact on the market. Higher rates mitigate affordability for buyers and reduce purchasing power. As rates drop/level off, it’ll be valuable to compare rates against sales prices.

Flat. Nearly absolutely flat in terms of year over year changes. This seems fair given the conjunction of more inventory and slightly reduced demand.


Affordability

Affordability has improved by about 14%. Although mortgage rates are currently a little higher than they were this time last year, purchasing a home is now a little easier for current buyers for home prices that have softened. If rates or prices come down, this will continue to improve affordability.

Affordability, slowly but surely continues to improve marginally. If the changes don’t already seem negligible, let me reinforce it with a number: 2.8% improvement in affordability. With little to no changes in year over year pricing budding up against marginally improved interest rates, buyers are getting a slight relief in affordability.


Inventory

Inventory ticked up by about 11%. This seems to support the picture of pricing coming down. With more inventory, there is less competition for buyers and greater opportunity to negotiate.

What did change significantly is the increase in inventory. Our inventory grew by more than 26%. This jump would be very concerning if we weren’t in a high demand marketplace like Southern California. The other variable in this is that a lot of these sellers have a lot of equity in their homes. The sale isn’t the house of cards that drove a lot of the recession. A lot of that is about changing lending practices as a side effect of the recession.


Year over year volume of sales

On the other hand, we had a nearly 10% increase in the volume of sales. Deals got done. Buyers could negotiate. This also seems to support the idea that we aren’t crashing. Demand is still strong. However, it is muted with lower affordability in contrast to. years past.

Not quite proportionately with the increased volume of inventory, we also have an increased volume in sales. Our volume of sales increased by just over 17%. I mention the increased inventory in correlation as it reflects ongoing demand. As long as both sales volume and inventory are moving in the same direction, the market is communicating clearly: we still have good demand.


List price versus Sale Price

Ultimately, this ratio didn’t change. Sellers met the market.

Our list price versus sale price increased by 1%. This number in conjunction with our increased volume of inventory are definitely indicating the significance of pricing properties correctly.


Year over year changes in days on market

Average days on market came down. Demand is still relatively strong.

Our average days on market continued to come down by 14%. It also demonstrates that when sellers want to sell, they price their property well and meet the market.


Uncategorized • January 3, 2025

New Year, Market Changes

It’s the beginning of a new year!! Time to look at how our market has changed over the course of the year.


Rates

Yes the fed has dropped the federal funds rate. However, according to Mortgage News Daily , mortgage rates haven’t progressively decreased. As of right now, the expectation is for two more fed rate cuts. This doesn’t directly correlate to lower mortgage rates. At a minimum, the hope is for mortgage rates to not increase.


Rent growth opportunity for first half of 2025

Because inflation has still been relatively high, most landlords will be able to increase rents by 8.9% until July 31, 2025. The general rule of thumb is 5% plus CPI with a cap of 10%. This doesn’t mean that all rents are up by 8.9%. Given that CPI is likely to come down with the Fed’s effort to combat inflation, there might not be opportunity to charge rent at an increase of 8.9%. It is probably most applicable for long term tenants who are currently under market.


Year over Year changes in Sales Price

Over the course of the past year, our average sale price slumped by nearly 20%. This is a good reflection of lower rates having a strong impact on the market. Higher rates mitigate affordability for buyers and reduce purchasing power. As rates drop/level off, it’ll be valuable to compare rates against sales prices.


Affordability

Affordability has improved by about 14%. Although mortgage rates are currently a little higher than they were this time last year, purchasing a home is now a little easier for current buyers for home prices that have softened. If rates or prices come down, this will continue to improve affordability.


Inventory

Inventory ticked up by about 11%. This seems to support the picture of pricing coming down. With more inventory, there is less competition for buyers and greater opportunity to negotiate.


Year over year volume of sales

On the other hand, we had a nearly 10% increase in the volume of sales. Deals got done. Buyers could negotiate. This also seems to support the idea that we aren’t crashing. Demand is still strong. However, it is muted with lower affordability in contrast to. years past.


List price versus Sale Price

Ultimately, this ratio didn’t change. Sellers met the market.


Year over year changes in days on market

Average days on market came down. Demand is still relatively strong.

Uncategorized • September 4, 2024

Cooling Market, but….

It’s subtle, but the market is slowly cooling. We’re seeing less new inventory. The existing inventory is becoming stale. The number of escrows is down significantly. All of this being said, we still only have 4 months supply of inventory. That may suggest that we’re not in a buyers’ market yet. List price versus sale price is tending down, but really negligible. Finally, pricing is relatively flat for the last 4 months.

So what’s the takeaway? We appear to have 3 different variables all working in conjunction with one another: rates, inventory and pricing. It appears that an awful lot of buyers are happy to wait for lower rates. We are not seeing more new inventory, but the existing inventory is hanging around. Some of the pent up inventory is waiting for lower rates too. Most homeowners are experiencing the golden handcuffs effect where they don’t want to give up their low interest mortgages to take on much higher rates for a preferred home.

Prices held firm through rate hikes because our inventory and volume of transactions plummeted in comparison. Good news for all parties involved, rates are dropping. Lower rates makes the exact same price for a home more affordable. Just like prices held through rate hikes because of low inventory, if inventory is rising and rates are dropping this ought to provide justification for prices to stay steady or increase. This would increase affordability without increasing prices and open the door for a lot more transactions for both buyers and sellers.

Uncategorized • August 20, 2024

Current Rents, Pro Forma Rents and Market Rents: How are they all different?

When looking to acquire a multi family property, oftentimes there are two different rents advertised: current rents and pro forma rents. Just to complicate things further, there is also market rents and they can all vary wildly. It’s important to understand the difference. Here’s how to think about it.


Evaluating multi family properties can seem fairly straight forward. Use either a cap rate or gross rent multiplier against what the property is generating and calculate the value of the property from there. However, this doesn’t take into account disengaged landlords and Covid.

It’s not uncommon for me to see a number of properties where rents are roughly 50% below their highest and best use. Whether this is a result of a disengaged landlord who doesn’t give their tenant rent increases or the landlord was already behind and couldn’t catch up with new Rent Cap laws, sometimes rents end up below market. On the flip side, sometimes rents can be artificially inflated because the property is being rented on a short term basis. Typically when properties are being rented on a short term basis, the expenses are higher and you eventually see this in the net operating income.

To bring rents up to market, normally this means that there is significant investment on the part of the new owner to bring the property to its highest and best use. This normally includes paint, bathroom and kitchen remodels, new lighting and flooring. Trying to calculate what the difference might be to convert a short term rental property to long term is a bit of a shot in the dark. Location typically has the greatest affect, but still challenging to calculate.


Next, and this is where I really come into play, knowing how to compare current rents, pro forma rents, versus market rents. Current rents is simply what the property is currently generating. If you know the rental market, you’ll know if this owner has been working to stay close to market or if they’re just happy to have the property rented and haven’t increased rent on their tenants in years. Pro forma rents are the anticipated rents if the owner is to replace the tenants. Sometimes the listing agent is taking into account that the new owner will remodel the property such that he or she can charge market rent. However, I’m always a little skeptical of pro forma rents because you don’t want to purchase a property with a miscalculated after repair value for rent.


It’s not weird to see pro forma rents vary from the current rental income. It’s also important for you to know what the market rents are in order to know how neglected the rents are or how artificial the pro forma rates are. Also, sometimes the pro forma rates can be low in anticipation that the incoming buyer will not remodel the property to its highest and best use.

Uncategorized • August 14, 2024

Affordability Changes

Affordability is a severely neglected topic. We talk plenty about interest rates and house prices, but talking about affordability and what that conjunctive picture looks like would provide some significant clarity.

Affordability is the conjunction of your house price and your interest rate. If we include wages, that tells a story of what percentage of the population can afford the home. For now, I’ll focus on house price and interest rates.

Now that rates have come down, affordability has definitely changed. Despite the fact that homes are worth more right now than they were this time last year, with lower interest rates, we actually have lower monthly costs and increased affordability. Month over month, affordability hasn’t changed. However, that is likely to change as we anticipate rates continuing to drop.

As affordability improves, I suspect we will begin to see more inventory, and probably more transactions. The average monthly price of a home with 20% down and the corresponding interest rates for the last year are as follows:

2024: $20,586.96

2023: $18,190.72

2022: $15,397.98

2021: $9,9765.26

2020: $9,187.85

2019: $9,263.34


Affordability Video-Reports on Housing

Uncategorized • August 13, 2024

August Mid Month Market Update

Our market is demonstrating slowing demand and increasing inventory. Our days on market is increasing and for the first time in a long time, buyers are able to negotiate and homes are selling for 97% of their list price.

I think many people have a tendency to look for signs of a slip in our market. However, it appears that we are adjusting to a more normal territory. Buyers can expect to negotiate. There aren’t multiple offers within the first several days. A fair market is described as 6 months of supply. As of right now, we’re currently at just over 4 months. This would indicate that it’s still a seller’s market. However, I think our baseline as a result of COVID is so far out of whack that normal seems inappropriately slow. It’s like part of a conversation I had today: “rather than going from 30 miles per hour to 20 miles per hour, it’s like we’re going from 70 miles per hour to 50 miles per hour”. We’re definitely moving forward, we’re just slowing our acceleration.

I think the important note is that the Fed has the ability to decrease rates if they feel it’s appropriate in order to stimulate the economy. Last week there was definitely concern related to the Sahm Rule being triggered. However, how do we put that in context of record low unemployment for such a lengthy period of time. Even with where unemployment is now, we’re still below our historical average. Unemployment

If we have approached a more fair market and we can’t anticipate ferocious nominal price growth, our affordability will likely increase as rates come down. In general I anticipate that the volume of transactions will begin to increase as more people begin to decide that another home would be a better fit. Better than their low interest rate. It may take a quiet winter, but housing has always been resilient and I don’t suspect that will change as people will always need a place to live.

Uncategorized • July 23, 2024

Changes in interest rates without Fed interference


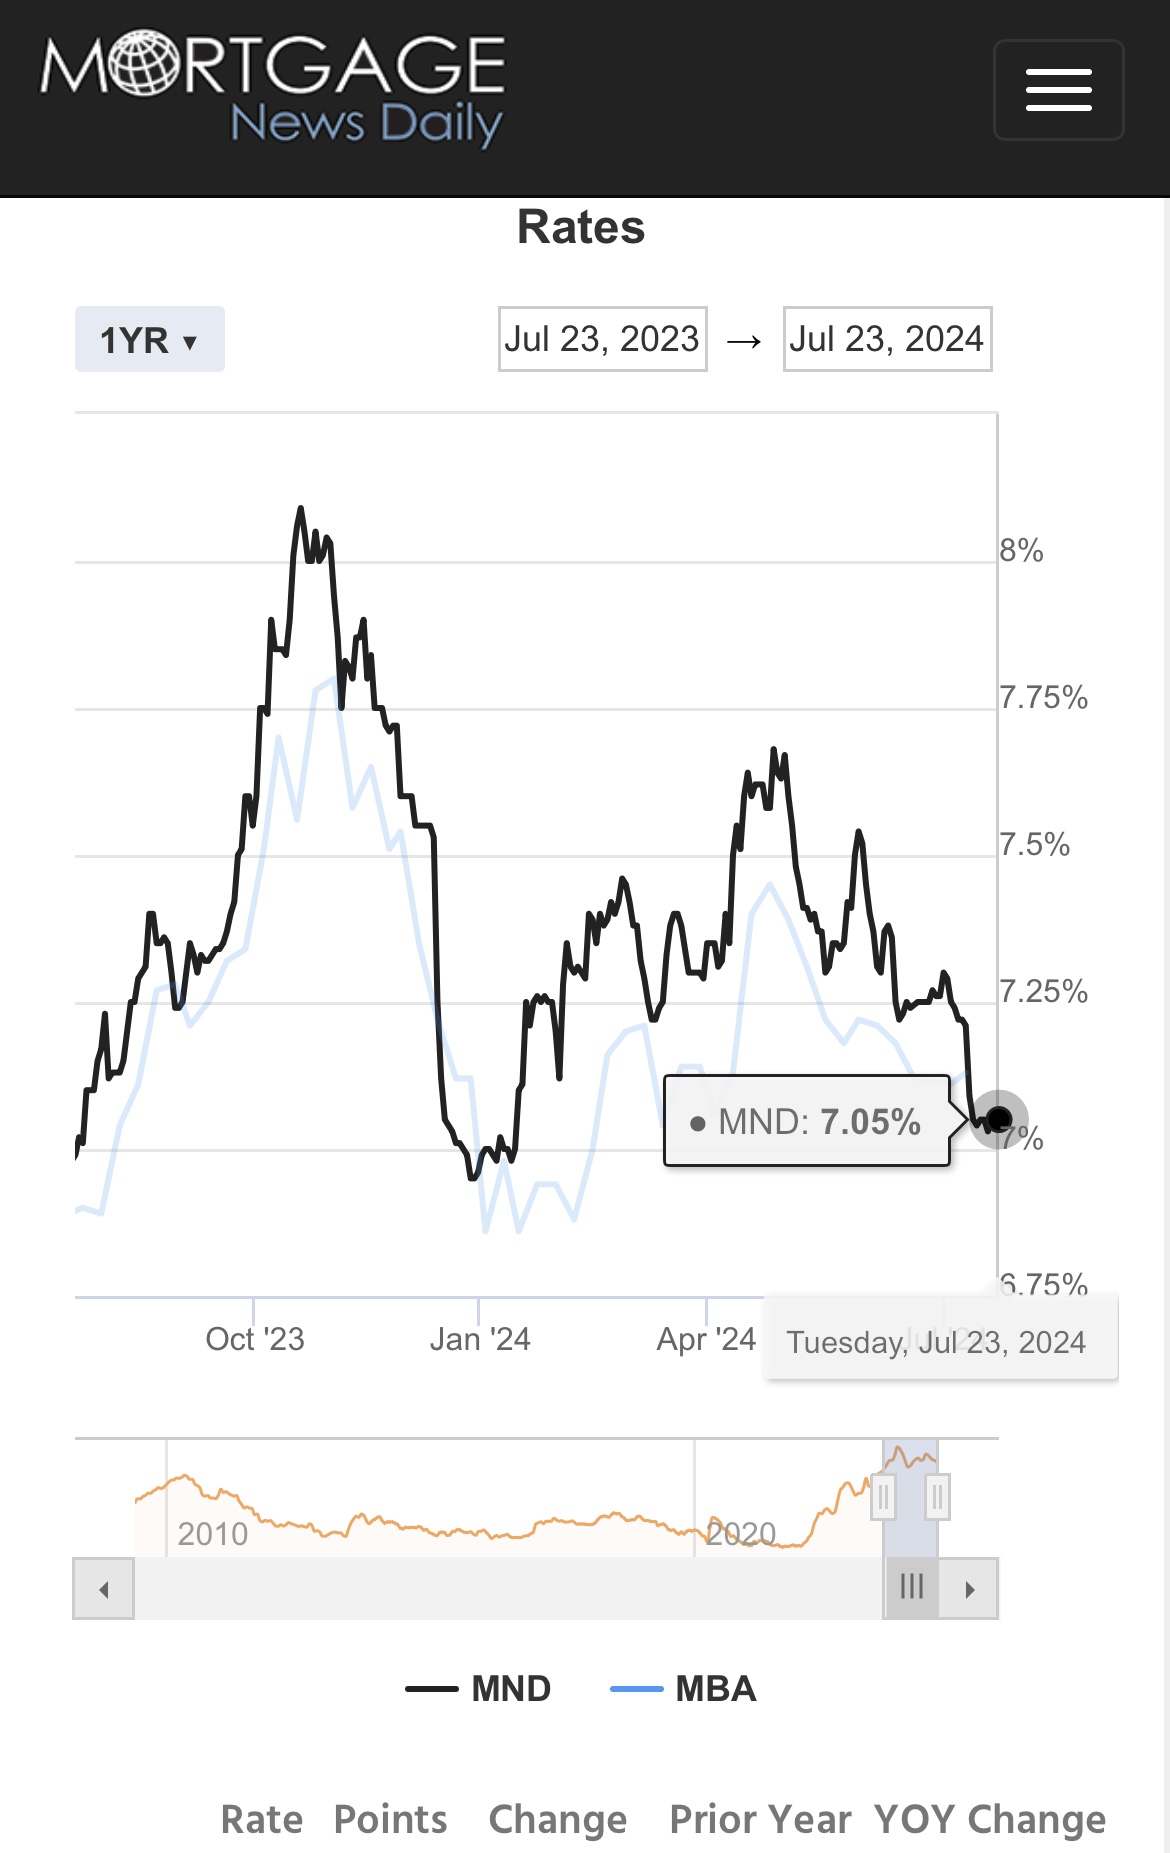
In case you’ve been living under a rock, interest rates have ticked up. However, it has been over a year since we have incurred any rate hikes. What becomes even more interesting is when you stop and look at the significant changes in rates, despite Federal Reserve intervention. Why does this occur?

There are a couple things. I’m going to focus on the bank side and business side of rate changes. We had a massive drop in January because it was preceded by the Fed announcing that they were hopeful that they were done increasing rates. The banks heard that news and were able to cut rates because they no longer needed as significant a margin in order to protect themselves to secure profitability. A lender I know constantly tells me that based on where bond rates are, mortgage rates should be significantly lower, but they weren’t.

The bottom line is/was that the banks were nervous. They were hedging their bets. When we didn’t have a huge crash and still had continued, positive growth through the spring, we prohibited the fed from being able to come out and cut rates. Translation: we were too resilient. That brings us to our spike towards the end of April and beginning of May.

Flash forward to between May and now, we’re just waiting. As I said before, it has now been more than a year since the Federal Reserve intervened with rates. Given where the health of the economy is now, there doesn’t appear to be any anticipation of a rate hike. We’re just waiting on a cut. When that happens stay tuned. However, even if we get a rate cut, it doesn’t mean that we will have a strongly correlated reduction in mortgage rates as demonstrated by the significant swings we’ve had in just the last year.

Uncategorized • July 22, 2024

Market Update-Increasing Inventory, Decreasing Escrows

I noted this last month and it’s roughly the same story: more inventory and fewer escrows. In contrast to last year, we have a nearly 17% increase in inventory, but a 10% decrease in the volume of escrows. This is another indicator that our market is slowing down. In contrast to the year before Covid, we’ve got nearly half the inventory and a little more than 50% more in inventory. Proportionately, now we’ve got about 22% in escrow. Last year it was 28%. The year before COVID we had about 19% of our inventory in escrow.


So what does all of this mean? This is an indication of still relatively low demand correlating with low inventory, but that correlation is weakening. This is a reflection that we are definitely not likely to see 20% year over year growth. However, we still have a higher percentage of inventory currently in escrow than we did prior to Covid reflecting a relatively stable or strong market. We probably will continue to have growth, just less than we did through Covid.


We also have a couple of external variables that may be affecting this market: the election and impending changes to interest rates. It’s astonishing to hear how many people would rather suspend their sale either listing their home or purchasing their home. As a result, we might have artificially low numbers for both listings and escrows. Couple this with the growing anticipation of rate decreases and we have another reason for artificially low listings and escrows.

No one has a crystal ball. However, I think there is excellent justification for a rip roaring spring 2025. In the meantime and for additional input in our current, buyer trending market, take a look at the article below. Watch Months-of-Supply